Moflow+

In retirement, how long will the money last?

The earliest age your capital reaches 25× your yearly spend, and how long it lasts once you retire.

Try Moflow+

Moflow+ · $199 per year

An estimate from assumptions you supply, not a forecast. Not investment advice — decisions are yours.

  1. When, and how much

    The earliest age, how long the money lasts, and what is still to go.

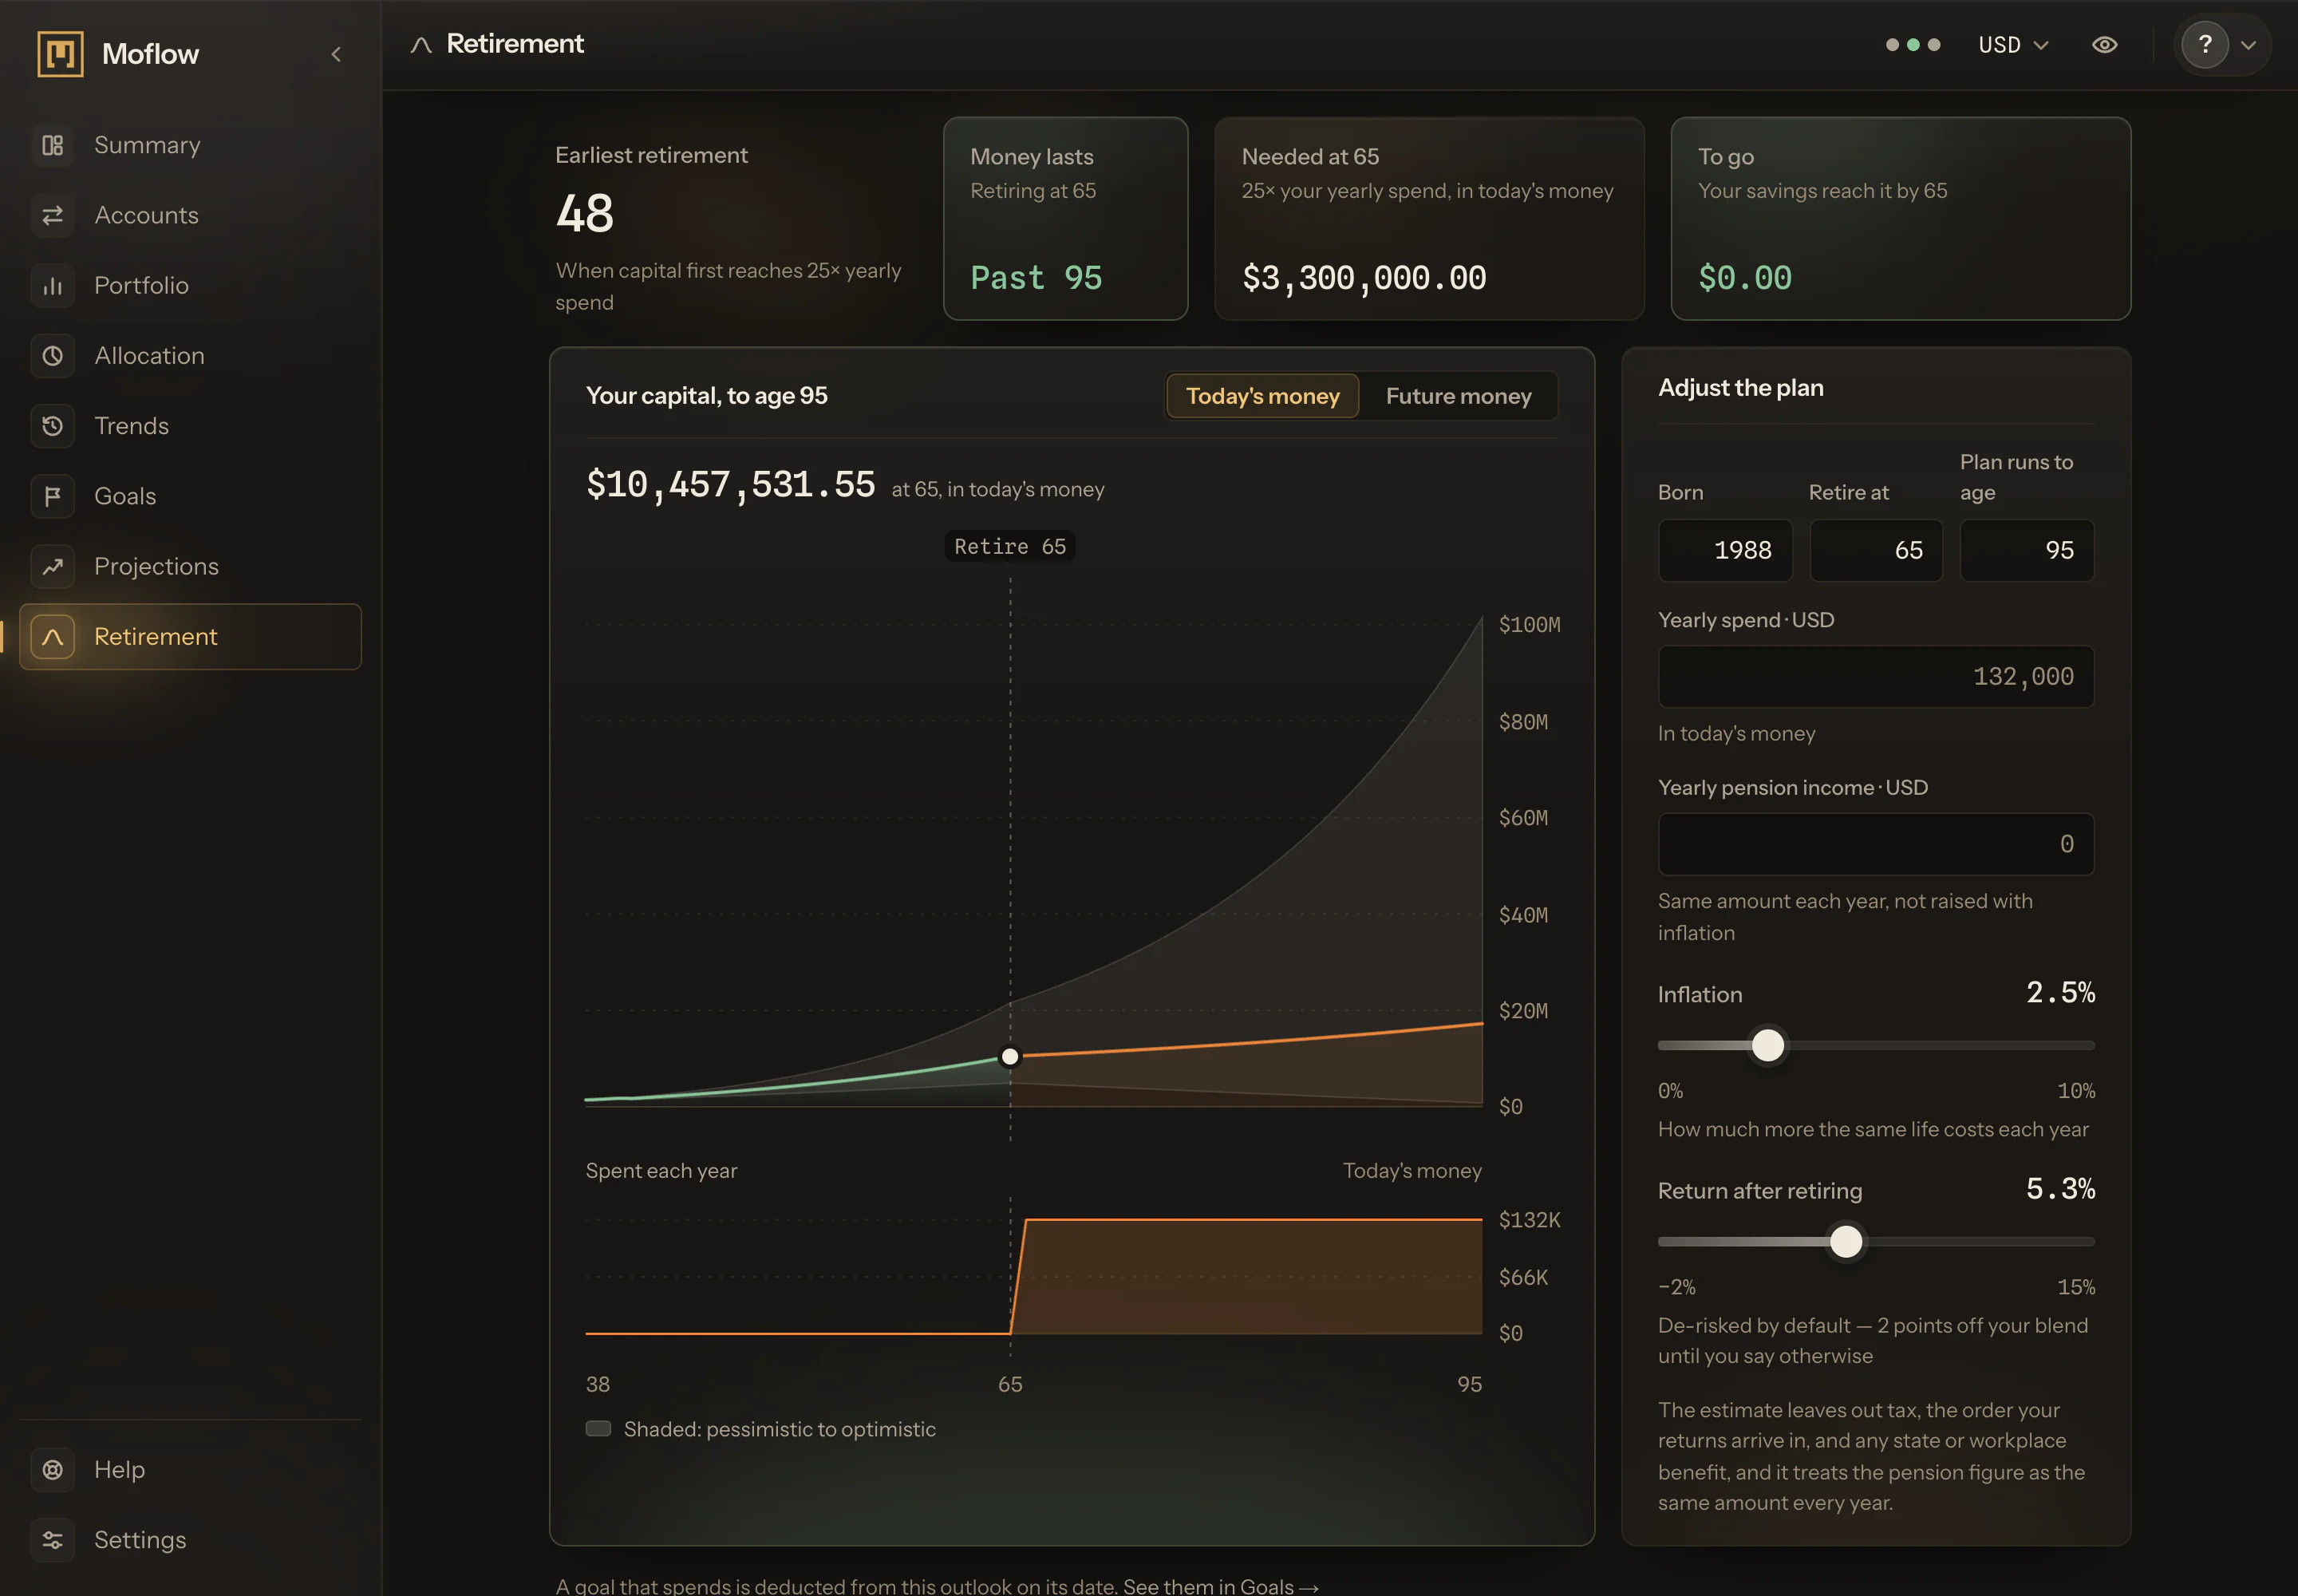
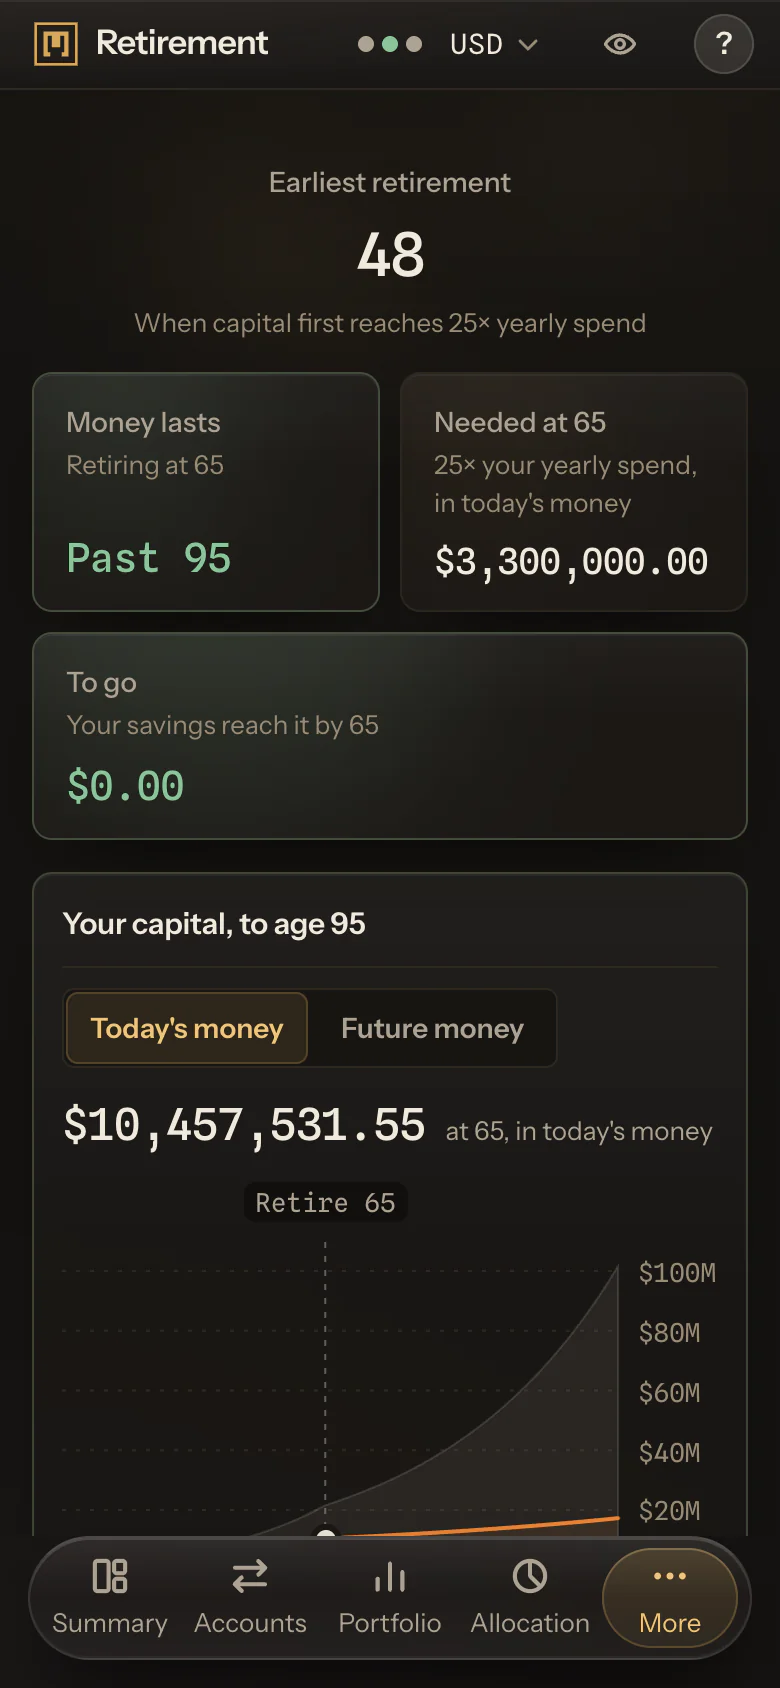
    In the frame, the figures sit in a row: Earliest retirement, Money lasts, Needed at 65 and To go. Three answers sit side by side.

    Earliest retirement is the first age your projected capital reaches 25× your yearly spend. Money lasts is the age it runs out after you retire, or Past 95 if it lasts the whole plan.

    Needed is 25× your yearly spend in today's money, with what is still to go beneath it. The three questions of retirement, answered from your own figures.

    Earliest retirement is a different figure from the age you plan to retire at. One is the first age the capital could carry your spending; the other is the age you chose, and Money lasts is measured from it.

  2. Year by year

    Your capital and what you spend each year, in today's or future money.

    In the frame, the capital climbs to the retirement age and draws down after it, with each year's spending beneath. Before you retire, the capital follows your projection.

    After, each year it earns its return, pays your spending and takes in your pension, if you have one.

    Spending rises with inflation, 2.5% a year to start, and the chart reads in today's money or in future money. You see the whole retirement, not just the day it starts.

    If the capital runs out before the plan ends, the chart marks the year it reaches zero. If the curve dips below zero before you retire, because a goal spends money that is not there, Money lasts reads Below zero at that age.

  3. Change the plan

    Set when you retire, what you spend, your pension, inflation and returns.

    The plan starts at retiring at 65, with spending at twelve months of your burn rate; set your own figures for both. The return after retiring starts 2 points below the return before it.

    Move one lever, and the three answers and the chart redraw together. The plan runs to age 95, and you can end it at another age.

    Try a different age or spend, and the answers follow. Every lever starts from a value Moflow fills in, so the page answers before you set anything.

A worked example: how long 1,200,000 lasts

One spend, one capital, and a pension added. Say your yearly spend is 60,000 USD. Needed at 65 reads 1,500,000 USD: 25× that spend, in today's money.

Suppose the projection reaches 1,200,000 USD at 65, so 300,000 USD is still to go.

To keep the arithmetic plain, set inflation and the return after retiring to 0%. Each year then takes 60,000 USD out, and Money lasts reads To age 85: twenty years of spending. Twenty years at 60,000 is the 1,200,000 to the dollar, which is what makes the plain case easy to follow.

Add a pension of 12,000 USD a year. Each year now draws 48,000 USD from the capital, and Money lasts reads To age 90.

At 1,500,000 USD and no pension, the same plain plan lasts 25 years, To age 90. With inflation and a return set, the same plan gives a different age. These figures are an estimate from the assumptions above, not a forecast.

How much do I need to retire?

Moflow's Needed figure is 25 times your yearly spend, in today's money: 1,500,000 for a spend of 60,000. It comes from a 4% yearly withdrawal, a rule of thumb rather than a guarantee, and it leaves out tax.

At 25×, a spend of 40,000 reads 1,000,000.

How long will my money last in retirement?

Moflow runs your capital forward a year at a time: its return in, your spending out, your pension in. The age it runs out is the answer, or Past 95 if it lasts the whole plan.

With no return and no inflation, it is the capital divided by the yearly draw.

Does the retirement plan account for inflation?

Yes. Spending rises each year at the inflation rate you set, 2.5% to start, and the chart can show today's money or future money.

Your pension stays flat. At 2.5%, a spend of 60,000 today is about 76,805 in ten years.

Can I include a pension in the retirement plan?

Yes. A yearly pension enters from your first year of retirement as a flat amount, so it does not rise with inflation. Each year it covers part of your spending, and the capital pays the rest.

A pension of 12,000 against a spend of 60,000 leaves 48,000 to draw each year.

Is this financial advice?

No. Moflow shows what your own figures imply, and the decisions are yours. The fine print under the chart says the same: an estimate, not a forecast.

What is the 4% rule?

A rule of thumb that sets the capital to retire on at 25 times a year's spending, because 4% of 25 times is one year.

Moflow uses it for Needed and Earliest retirement; Money lasts runs the plan year by year instead.

The ledger is free. Moflow+ runs the numbers.

Trends, goals, projections and retirement, drawn from the same ledger.

Try Moflow+

Moflow+ · $199 per year